Jeff Cost

Cincinnati Home Loan

  • Home
  • About
    • About Us
    • Privacy Policy
  • Blog
  • Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Loan Checklist
    • Loan Programs
    • Loan Process
    • Mortgage FAQ
    • Mortgage Glossary
    • Get a Rate Quote
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply Now
    • Online Application
    • Home Purchase
    • Home Refinance
    • Loan Comparison
  • Reviews
    • Leave a Review
  • Contact

Ready to Buy Your First Home? Don’t Forget to Check Your Credit Score – Here’s Why

September 6, 2017 by Jeff Cost

Ready to Buy Your First Home? Don't Forget to Check Your Credit Score – Here's WhyWhether you’re just out of college, recently married or simply haven’t jumped into the market yet, buying your first home is an exciting prospect. It can also be an expensive one, which is why most people will take out a mortgage to help finance the cost.

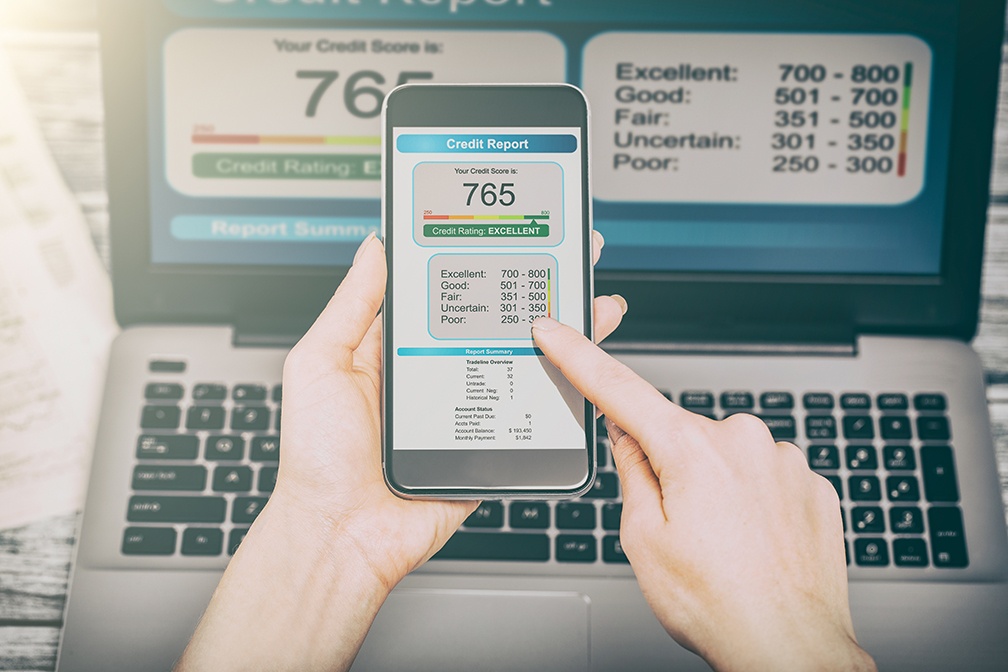
If you are planning on engaging with a mortgage lender, you’ll need to have your finances in order. In today’s post, we’ll share a few key reasons why you’ll want to check your credit score well in advance of buying your first home.

Your Credit Score Is A Signal For Lenders

As you know, mortgage lenders have a responsibility to lend to those individuals and families who are at a low risk of default. So when a mortgage lender starts to dig into your financial background, they are looking at your credit history and credit score to help them assess that risk.

Note that having a low score doesn’t necessarily mean you have bad credit. If you’re still in your 20s and have only had a credit card, your score might be low even though you are fully capable of managing a mortgage.

Your Score Impacts Your Mortgage Interest Rate

As mentioned above, your credit score helps to signify your risk. If your credit score is in a lower range, perhaps a 640 or 660, you’re presenting a greater risk than someone with a score of 760 or 800. Because of this, the interest rate that you pay on your mortgage will in part be determined by your credit score. Those individuals who present a higher risk pay a higher rate to compensate. And vice versa, if your credit is spotless you can expect to pay a lower interest rate.

You’ll Need Time To Challenge Any Issues

Finally, you’ll need to give yourself some lead time to challenge any irregularities with your credit report. The credit reporting agencies aren’t perfect and they do make mistakes. There may be some old, retired credit card or other debt sitting on your report which is holding the score down. Even worse, there may be some incorrect delinquency or other error which ends up as a big red flag for potential mortgage lenders.

As you can see, it’s worth spending the time to check your credit score. You get to check it for free once per year, so take advantage of the opportunity. And when you’re ready to discuss buying your first home, contact your trusted mortgage professional. We’ll share how to navigate the credit score and mortgage process so you can land the home of your dreams.
Filed Under: Home Buyer Tips Tagged With: Buying A Home, Home Buyer Tips, Real Estate Tips

Ready to Buy Your First Home? Don’t Forget to Check Your Credit Score – Here’s Why

September 6, 2017 by Jeff Cost

Ready to Buy Your First Home? Don't Forget to Check Your Credit Score – Here's WhyWhether you’re just out of college, recently married or simply haven’t jumped into the market yet, buying your first home is an exciting prospect. It can also be an expensive one, which is why most people will take out a mortgage to help finance the cost.

If you are planning on engaging with a mortgage lender, you’ll need to have your finances in order. In today’s post, we’ll share a few key reasons why you’ll want to check your credit score well in advance of buying your first home.

Your Credit Score Is A Signal For Lenders

As you know, mortgage lenders have a responsibility to lend to those individuals and families who are at a low risk of default. So when a mortgage lender starts to dig into your financial background, they are looking at your credit history and credit score to help them assess that risk.

Note that having a low score doesn’t necessarily mean you have bad credit. If you’re still in your 20s and have only had a credit card, your score might be low even though you are fully capable of managing a mortgage.

Your Score Impacts Your Mortgage Interest Rate

As mentioned above, your credit score helps to signify your risk. If your credit score is in a lower range, perhaps a 640 or 660, you’re presenting a greater risk than someone with a score of 760 or 800. Because of this, the interest rate that you pay on your mortgage will in part be determined by your credit score. Those individuals who present a higher risk pay a higher rate to compensate. And vice versa, if your credit is spotless you can expect to pay a lower interest rate.

You’ll Need Time To Challenge Any Issues

Finally, you’ll need to give yourself some lead time to challenge any irregularities with your credit report. The credit reporting agencies aren’t perfect and they do make mistakes. There may be some old, retired credit card or other debt sitting on your report which is holding the score down. Even worse, there may be some incorrect delinquency or other error which ends up as a big red flag for potential mortgage lenders.

As you can see, it’s worth spending the time to check your credit score. You get to check it for free once per year, so take advantage of the opportunity. And when you’re ready to discuss buying your first home, contact your trusted mortgage professional. We’ll share how to navigate the credit score and mortgage process so you can land the home of your dreams.

Filed Under: Home Buyer Tips Tagged With: Buying A Home, Home Buyer Tips, Real Estate Tips

What’s Ahead For Mortgage Rates This Week – September 5, 2017

September 5, 2017 by Jeff Cost

Last week’s economic reports included readings on home prices, pending home sales and construction spending. Weekly reports on mortgage rates and new jobless claims were released along with labor-sector readings on Non-Farm Payrolls, ADP employment and National Unemployment.

Case–Shiller: Three Western Cities Hold Top Three Places for Home Price Growth

According to Case-Shiller’s June edition of its 20-City Home Price Index, the top three spots were again held by Seattle, Washington, Portland Oregon and Dallas, Texas. Seattle home prices outstripped Portland, Oregon with a reading of 13.40 percent home price growth on a seasonally-adjusted annual basis. Portland, Oregon home prices grew by a seasonally-adjusted year-over-year rate of 8.20 percent while Dallas, Texas held third place with its year-over-year reading of 7.70 percent growth.

 David Blitzer, CEO and Managing Director of S&P’s Index Committee, said that he sees no indications that home prices will cool anytime soon. Strong labor markets and economic growth are encouraging home buyers while low inventories of homes for sale coupled with high demand continued to fuel home price growth.

Construction spending dipped in July by -0.60 percent as compared to expected growth of + 0.60 percent and June’s reading of 1.30 percent growth in spending. Real estate pros said that building more homes is the only way to ease demand for homes, but builders cited labor and lot shortages along with rising materials costs as obstacles to building more homes faster.

Mortgage Rates Fall, Weekly Jobless Claims Rise

Mortgage rates remain relatively low; Freddie Mac reported average mortgage rates for a 30-year fixed rate mortgage fell four basis points to 3.82 percent; interest rates for a 15-year fixed rate mortgage were four basis points lower at 3.12 percent and the average rate for a 5/1 adjustable rate mortgage was three basis points lower at 3.14 percent. Discount points averaged 0.50 percent for all three mortgage types.

First-time jobless claims rose by 1000 claims to 236,000. Analysts had expected no change from the prior week’s reading of 235,000 new jobless claims.

ADP payrolls rose to 237,000 new jobs reported for August as compared to 201,000 new private-sector jobs reported in July. The Bureau of Labor Statistics reported 156,000 new public and private sector jobs in August; Based on the ADP report and the expected reading of 170,000 new public and private-sector jobs, revision of the Non-Farm Payrolls report appears likely.

The National Unemployment rate ticked up from July’s reading of 4.30 percent to 4.40 percent in August. Low readings for unemployment indicate that layoffs are not significantly contributing to unemployment.

What‘s Ahead

No financial reports will be issued Monday in observance of the Labor Day Holiday. The Federal Reserve’s Beige Book report will be released along with reports on productivity and weekly readings on mortgage rates and new jobless claims.

Filed Under: Mortgage Rates Tagged With: Mortgage Rates

  • « Previous Page
  • 1
  • …
  • 760
  • 761
  • 762
  • 763
  • 764
  • …
  • 1276
  • Next Page »

Jeff Cost
Sr. Loan Officer

Cincinnati, OH Mortgage Lender
NMLS# 21688


jeffrey.cost@ccm.com

Call (513) 403-6260
Fax (941) 567-5222

Cross Country Mortgage

How can I help?

Connect with Me!

Browse Articles by Category

The Latest Articles

  • Why a Condo’s Finances Can Matter Almost as Much as Yours When Getting a Mortgage
  • What Happens When the House You Want Has a Solar Loan Attached to It?
  • Could Paying Off a Debt Before Applying for a Mortgage Actually Be the Wrong Move?
  • Why Your First Mortgage Payment Might Be Farther Away Than You Expect
nmlsconsumeraccess.org
Equal Housing Lender

Our Location

CrossCountry Mortgage, LLC
4050 Executive Park Drive, Suite 220
Cincinnati, OH 45242

Personal NMLS21688 Branch NMLS2458257
Company NMLS3029

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in