Jeff Cost

Cincinnati Home Loan

  • Home
  • About
    • About Us
    • Privacy Policy
  • Blog
  • Resources
    • First Time Seller Tips
    • First Time Buyer Tips
    • Home Appraisal
    • Loan Checklist
    • Loan Programs
    • Loan Process
    • Mortgage FAQ
    • Mortgage Glossary
    • Get a Rate Quote
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply Now
    • Online Application
    • Home Purchase
    • Home Refinance
    • Loan Comparison
  • Reviews
    • Leave a Review
  • Contact

Loans For Underwater Homeowners : HARP 2.0 Now Available

March 20, 2012 by Jeff Cost

Making Home Affordabie

The new, revamped HARP program is now available in Kentucky and   nationwide. It was officially released Saturday, March 17, 2012 by Fannie Mae and Freddie Mac.

HARP is an acronym. It stands for Home Affordable Refinance Program. HARP is the conforming mortgage loan product meant for “underwater homeowners”. Under the HARP program, homeowners in Columbus can get access to today’s low mortgage rates despite having little or no equity whatsoever.

HARP is expected to reach up to 6 million U.S. homeowners who would otherwise be unable to refinance.

HARP is not a new program. It was originally launched in 2009. However, the program’s first iteration reached fewer than 1 million U.S. households because loan risks were high for banks, and loan costs were high for consumers.

With HARP’s re-release — dubbed HARP 2.0 — the government removed many of HARP’s hurdles.

In order to qualify for HARP, homeowners must first meet 3 qualifying criteria. 

First, their current mortgage must be backed either Fannie Mae or Freddie Mac. Loans backed by the FHA or VA are ineligible, as are loans backed by private entities. This means jumbo loans and most loans from community banks cannot be refinanced via HARP.

  • To check if your loan is Fannie Mae-backed, click here.
  • To check if your loan is Freddie Mac-backed, click here.

The second qualification standard for HARP is that all loans to be refinanced must have been securitized by Fannie Mae or Freddie Mac prior to June 1, 2009. Mortgages securitized on, or after, June 1, 2009 are HARP-ineligible.

There are no exceptions to this rule.

And, lastly, the third HARP qualification standard is that the existing mortgage must be accompanied by a strong repayment history. Homeowners must have made the last 6 mortgage payments on-time, and may not have had more than one 30-day late within the last 12 months.

If the above three qualifiers are met, HARP applicants in Mason will find mortgage guidelines lenient overall :

  • Refinancing into a fixed rate mortgage allows for unlimited loan-to-value
  • The standard 7-year “waiting period” after a foreclosure is waived in full
  • Except in rare cases, home appraisals aren’t required for HARP

Furthermore, HARP mortgage rates are on par with non-HARP rates. This means that HARP applicants get access to the same mortgage rates and loan fees as non-HARP applicants. There’s no “penalty” for using HARP.

To apply for HARP, check with your loan officer today.
Filed Under: Mortgage Guidelines Tagged With: HARP, Making Home Affordable, Underwater

What’s Ahead For Mortgage Rates This Week : March 19, 2012

March 19, 2012 by Jeff Cost

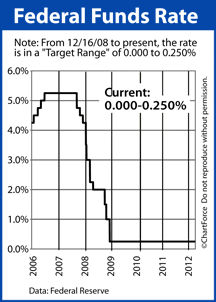
Fed Funds Rate 2006-2012Mortgage markets worsened last week as the Federal Reserve’s Federal Open Market Committee suggested economic recovery may be closer than it originally expected, and that inflation may be a near-term economic concern.
Although the FOMC voted to leave the Fed Funds Rate unchanged in its current range near 0.000 percent, its published comments sparked a broad-based mortgage bond selloff.

Conforming mortgage rates throughout OH rose sharply post-FOMC, climbing by as much as 0.375%.

If you’ve been shopping for a mortgage rate, the run-up was both untimely and unwelcome.

According to Freddie Mac’s weekly mortgage rate survey, for most of the year, conforming 30-year fixed rate mortgage rates had remained within a tight range near 3.90 percent for mortgage applicants willing to pay an accompanying 0.8 discount points.

This week, though, Freddie Mac is expected to report average 30-year fixed rate mortgage rates well north of four percent. It would mark the highest level for the benchmark mortgage rate since mid-December of last year.

There will be a lot more for rate shoppers to watch this week, too. There is a slew of housing data set for release and the heavily-anticipated HARP 2.0 Refinance program “goes live” nationwide.

HARP is a government-led refinance program meant to help underwater homeowners refinance their Fannie Mae- or Freddie Mac-backed mortgages into new loans at today’s low rates.

The program was first launched in 2009 and helped roughly one million U.S. homeowners. HARP’s newest iteration, though, provides for a more lenient underwriting process that is expected to open the program to an additional 6 million homeowners or more.

Mortgage rates may rise this week as a result of HARP-based loan volume. It may also rise on strength in housing — there are four data points due for release :

  • Monday : Housing Market Index
  • Tuesday : Housing Starts
  • Wednesday : Existing Home Sales
  • Friday : New Home Sales

As in most weeks, it’s less risky to lock a mortgage rate than to float one. Mortgage rates have much room to climb but very little room to fall. If you’re not yet locked, talk to your loan officer and make a plan.

Filed Under: Mortgage Rates Tagged With: FOMC, HARP, Inflation

Foreclosure Volume Slated To Rise This Spring

March 16, 2012 by Jeff Cost

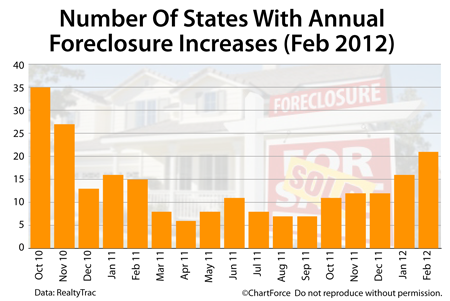
Foreclosure increases by state Feb 2012

After a series of months during which foreclosure volume was low, total filings have started to rise again, says RealtyTrac. 

In February, 21 states posted a year-over-year increase in monthly foreclosure filings, according to the national foreclosure-tracking firm. This is nearly twice as many states as compared to December 2011, marking the highest monthly reading since November 2010.

A “foreclosure filing” is defined to include any one of the following foreclosure-related events : (1) The serving of a default notice, (2) A scheduled home auction, or (3) A bank repossession.

Nationally, the number of foreclosure filings fell 2 percent from January. However, it’s a trend that may reverse. Foreclosure volume is expected to rise over the next few months.

This is because the $25 billion mortgage servicer settlement provides a framework for servicers to execute necessary foreclosures, from notice-to-auction. Some analysts believe that foreclosure filings were artificially depressed in 2011 because of the absence of such guidance. 

Like all things in real estate, though, foreclosures remain local.

For example, nationally, there was one foreclosure for every 637 housing units. On a state-by-state basis, however, the results looked different.  

  • Nevada : 1 foreclosure for every 278 housing units
  • California : 1 foreclosure for every 283 housing units
  • Arizona : 1 foreclosure for every 312 housing units
  • Georgia : 1 foreclosure for every 331 housing units
  • Florida : 1 foreclosure for every 341 housing units

Even on a city-by-city level, foreclosure concentration varied. Figures from several select cities include : 

  • Atlanta : 1 foreclosure for every 244 housing units
  • Chicago : 1 foreclosure for every 302 housing units
  • New York : 1 foreclosure for every 3,439 housing units
  • Seattle : 1 foreclosure for every 1,229 housing units
  • Washington : 1 foreclosure for every 1,198 housing units

One reason why foreclosure concentration is worth tracking is because homes in various stage of foreclosure are often sold at deep discounts as compared to similar, non-distressed homes. It’s no wonder foreclosed homes are in high demand among today’s Cincinnati home buyers. 

However, if you plan to buy a foreclosure in Kentucky , be sure to work with an experienced real estate agent. Foreclosed homes are often sold “as-is”, and may be defective at best and uninhabitable at worst. It makes good sense to have an advocate on your side to help with contracts and inspections.

Filed Under: Housing Analysis Tagged With: Distressed Homes, Foreclosures, RealtyTrac

  • « Previous Page
  • 1
  • …
  • 1212
  • 1213
  • 1214
  • 1215
  • 1216
  • …
  • 1275
  • Next Page »

Jeff Cost
Sr. Loan Officer

Cincinnati, OH Mortgage Lender
NMLS# 21688


jeffrey.cost@ccm.com

Call (513) 403-6260
Fax (941) 567-5222

Cross Country Mortgage

How can I help?

Connect with Me!

Browse Articles by Category

The Latest Articles

  • What Happens When the House You Want Has a Solar Loan Attached to It?
  • Could Paying Off a Debt Before Applying for a Mortgage Actually Be the Wrong Move?
  • Why Your First Mortgage Payment Might Be Farther Away Than You Expect
  • What’s Ahead For Mortgage Rates This Week – September 21st, 2026
nmlsconsumeraccess.org
Equal Housing Lender

Our Location

CrossCountry Mortgage, LLC
4050 Executive Park Drive, Suite 220
Cincinnati, OH 45242

Personal NMLS21688 Branch NMLS2458257
Company NMLS3029

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in